 Apollo
More than just an online quote
Simple online. Personal where it matters. Start your quote online, have a licensed agent review your options, and count on us to keep an eye on your policy. If a better option comes up, we’ll be here to help you take a look.
Get your quote online
Start with a simple online form. No long back-and-forth, no complicated process — just a faster, easier way to start shopping for coverage.
A real person reviews your options
Not just a quote — a quote checked by a person. Our technology helps gather and compare options, then a licensed Safe House agent reviews your rates, coverage, and details to help you find the right fit.
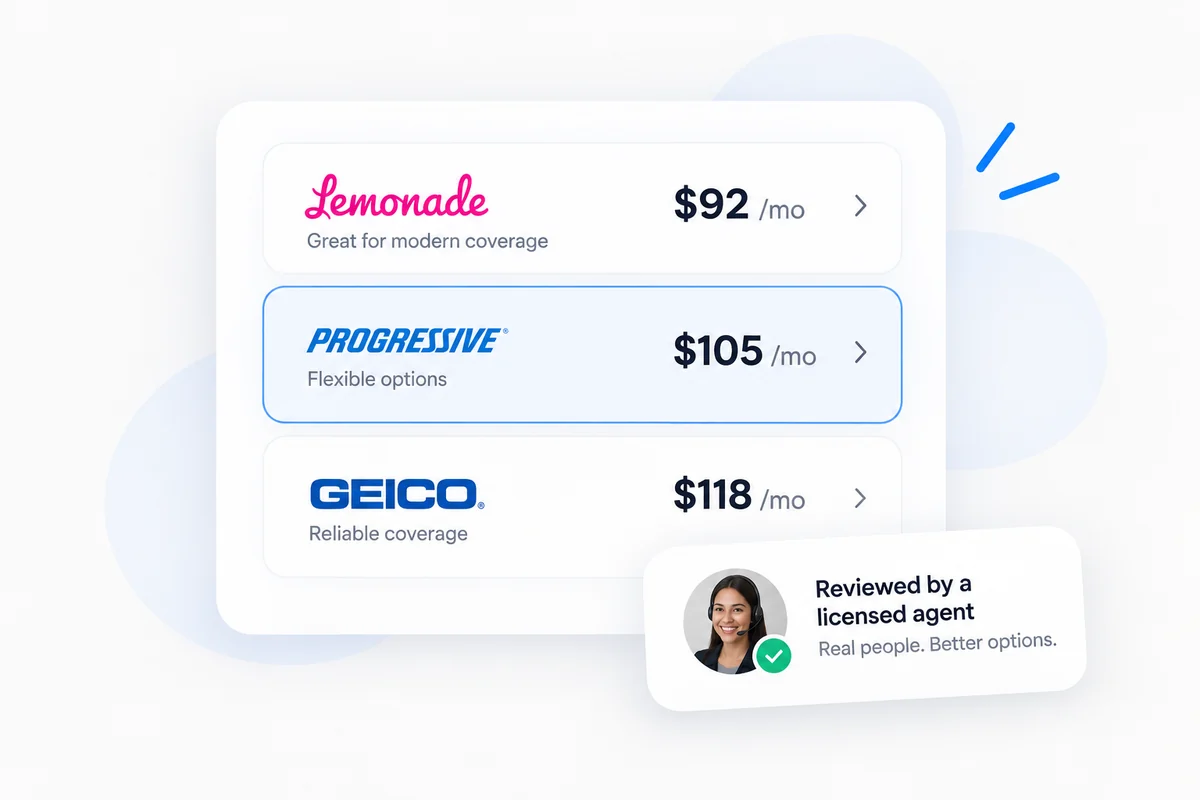
Illustration only — the figures shown are not real quotes.
We watch for better rates
We keep an eye on your policy, let you know when better options come up, and help you stay on top of renewals — with real support in English or Spanish.
What the online price misses
Uber and Lyft do carry insurance, and drivers reasonably assume that settles it. What it actually does is cover some periods of your shift and not others, and the places it stops are not obvious from the app.
This is the gap almost everyone has. You are logged in and waiting, so your personal policy treats you as working and the platform has not put you on a trip yet. Coverage in this window exists but it is much smaller than what applies once you are on a trip, and it is usually liability only — nothing toward your own car.
- Uber
- Lyft
- DoorDash
- Uber Eats
The platform’s comprehensive and collision generally only applies once you are matched or carrying a passenger, and it carries a deductible in the thousands. If you do not carry comprehensive and collision on your own policy, damage to your car in the waiting window is simply yours.
- Instacart
- Amazon Flex
- Grubhub
- Shipt
DoorDash, Uber Eats, Instacart, Amazon Flex and Shipt are a different exposure, and a rideshare endorsement frequently excludes them by name. A driver who added rideshare coverage and then started delivering is often uninsured for the delivery and does not know it.
- Part time and full time
- One car or several
- Financed or owned outright
If the carrier was never told you drive for a platform, the endorsement is not on the policy and the exclusion still is. The worst version is a claim denied for a trip you were being paid for, on a policy you had been paying for all along.
- Same-day proof of insurance
- Bilingual, start to finish
- Told plainly if we cannot beat what you have
Anyone can show you a number. A licensed Safe House agent reads the quote before you buy it, asks the questions above, and re-shops it when the answers change something. It costs you nothing — it is what the commission on the policy is for.
Three ways drivers cover this
Which one is right depends on how many hours you drive, whether you also deliver, and whether the car is financed. We will tell you which of these you actually need rather than selling you the largest one.
What is included
- Your normal personal coverage
- Extended while the app is on and unmatched
- Often extends your own comp and collision
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →What is included
- Everything above
- Food and parcel delivery included by name
- Checked against the platforms you actually use
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →What is included
- Written for business use from the start
- Higher limits available
- Covers employees and additional drivers
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →$•••/mo$•••/moYour two numbers, side by side — from a real quote, in about five minutes.
Compare between companies
The same driver, the same car, the same coverage — and the companies disagree, often by hundreds. One quote cannot tell you whether you are being charged too much, because there is nothing to compare it against. We put your details to every company we represent and show you what each one said.
A human reads every quote. That is the whole product. The form is the fast part; the part worth paying an agency for is somebody who has placed this a thousand times looking at what came back before you buy it.
Every platform, and the drivers other agencies find awkward.
Driving for a platform is not an edge case here. Neither is doing it with a record that makes a carrier think twice.
What people ask us
Does my regular car insurance cover me driving for Uber?
Almost certainly not while the app is on. A personal auto policy generally excludes carrying passengers or goods for a fee, and that exclusion is the default rather than the exception. It is worth reading your own policy for the words "livery" or "for hire" — and worth telling us what you drive for so the right endorsement goes on.
Doesn't Uber already insure me?
For part of your shift. Uber and Lyft both publish third-party liability of one million dollars while you are on the way to a rider and while a rider is in the car. Before either of those — app on, waiting for a request — the coverage is much smaller, and their comprehensive and collision only applies on a trip and carries a deductible in the thousands. The waiting window is where most drivers are uninsured without knowing it.
I only deliver food. Is that the same thing?
No, and this is the mistake that costs people. Many rideshare endorsements exclude delivery by name, so a driver who added rideshare coverage and then started delivering can be uninsured for the delivery. Tell us every platform you drive for — the wording has to match what you actually do.
Will telling my insurance company raise my rate?
Usually it costs something, and it costs far less than a denied claim. The larger risk is not the premium: it is a carrier discovering after a crash that you were working, which can mean the claim is denied and the policy cancelled. Tell them.
Which companies write rideshare in Texas and New Mexico?
Not all of them, and the list changes. That is what makes this worth shopping rather than accepting a single answer — the same driver can be quoted very differently depending on which carriers will write the exposure at all.
How fast can I get proof of insurance for the platform?
Usually the same day. Tell the agent up front that you need it for Uber or Lyft, because it changes which companies are worth quoting and getting that right the first time is the difference between driving tomorrow and not.
Let us take a second look.
Start online and an agent picks it up, or call and we will do the whole thing with you. In English or Spanish, whichever the conversation starts in.