 Apollo
More than just an online quote
Simple online. Personal where it matters. Start your quote online, have a licensed agent review your options, and count on us to keep an eye on your policy. If a better option comes up, we’ll be here to help you take a look.
Get your quote online
Start with a simple online form. No long back-and-forth, no complicated process — just a faster, easier way to start shopping for coverage.
A real person reviews your options
Not just a quote — a quote checked by a person. Our technology helps gather and compare options, then a licensed Safe House agent reviews your rates, coverage, and details to help you find the right fit.
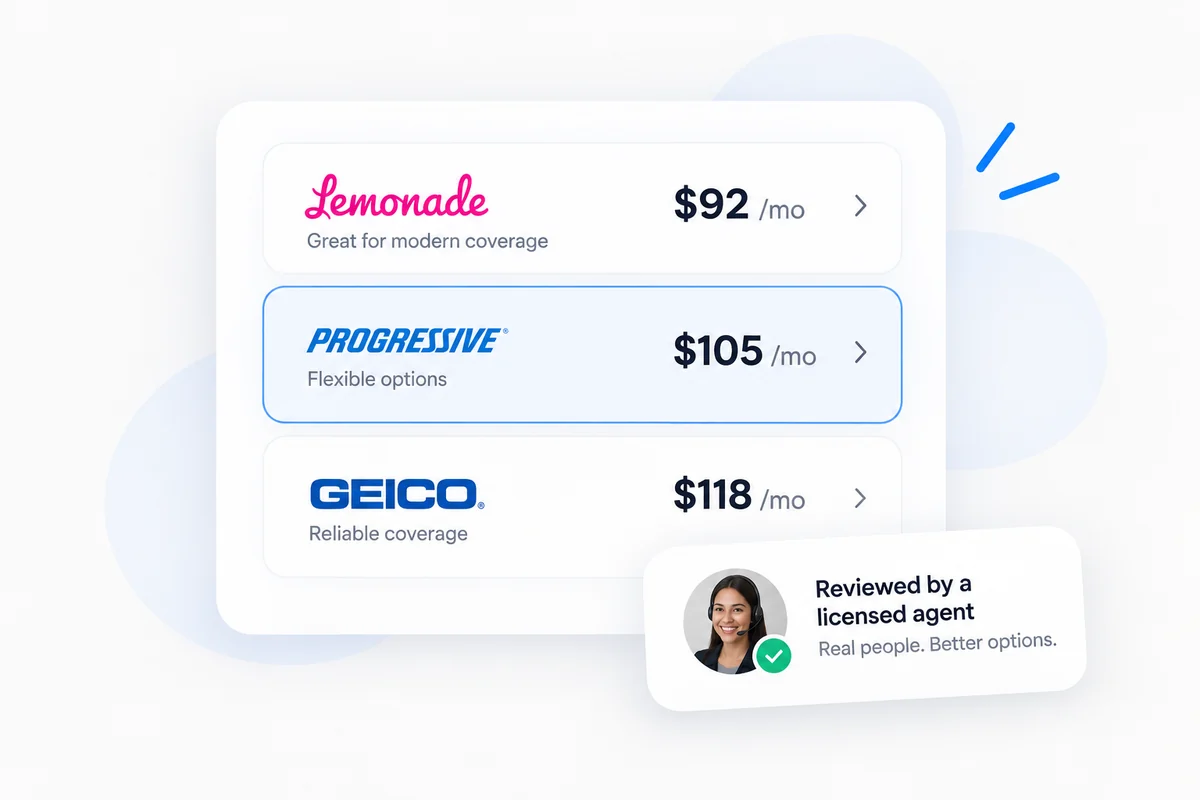
Illustration only — the figures shown are not real quotes.
We watch for better rates
We keep an eye on your policy, let you know when better options come up, and help you stay on top of renewals — with real support in English or Spanish.
What the online price misses
A home quote is only as good as the numbers it was built on, and an online form lets you get every one of them wrong without saying a word.
Not what you paid, not what the house would sell for — what a builder would charge to put it back, at today’s prices for labour and materials here. Insure it low and a partial claim can be reduced too. It is the single most common mistake on a home policy and a website cannot catch it.
Dwelling limit
Many policies in Texas and New Mexico pay a depreciated value for an older roof rather than replacing it, and some carry a separate wind and hail deductible that is a percentage of the house rather than a flat figure. Two quotes at the same price can be very different policies.
Roof settlement
Roof age and material, a monitored alarm, impact-resistant shingles, a newer electrical panel, gated community, bundling with the car. Carriers weigh these differently and the form does not ask about half of them.
- Roof age and material
- Impact-resistant shingles
- Alarm, and a water shutoff
- New-home credit
Flood is never in a homeowners policy and this is a region with dry ground and sudden water. Earth movement, sewer backup and a home business usually are not either. Better to find that out in a conversation than in a claim.
Flood and earthquake are never inside a home policy, anywhere. If you need them they are separate — and you should hear that from us now, not from an adjuster later.
Anyone can show you a number. A licensed Safe House agent reads the quote before you buy it, asks the questions above, and re-shops it when the answers change something. It costs you nothing — it is what the commission on the policy is for.
We lay the options out. You pick.
Home policies come in forms, and the form decides what is covered before any limit or deductible does. An agent tells you which one you are looking at and what changes if you move up.
What is included
- Fire, lightning and smoke
- Wind and hail
- Theft and vandalism
- The other causes named in the form
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →What is included
- The building, for anything not excluded
- Belongings, for the named causes
- Personal liability
- Loss of use while it is repaired
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →What is included
- The building, for anything not excluded
- Belongings, for anything not excluded
- Replacement cost, not depreciated
- Higher personal liability
- Scheduled items for the valuable things
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →$•••/mo$•••/moYour two numbers, side by side — from a real quote, in about five minutes.
Compare between companies
The same driver, the same car, the same coverage — and the companies disagree, often by hundreds. One quote cannot tell you whether you are being charged too much, because there is nothing to compare it against. We put your details to every company we represent and show you what each one said.
A human reads every policy. That is the whole product. The form is the fast part; the part worth paying an agency for is somebody who has placed this a thousand times looking at what came back before you buy it.
What we write
Homeowners is not one product. What you own and how you use it decides which companies will even look at it.
What people ask us
How much coverage do I need on the house?
Enough to rebuild it, which is rarely what you paid and never what a website guesses. Tell us the square footage, the year, the roof and the finishes and we will work it out with you.
Does home insurance cover flood?
No. It never does, anywhere, and that surprises people every single time. Flood is a separate policy and it is worth asking about here even away from a river.
My roof is old. Can I still get covered?
Usually, but it changes which companies will write it and how they pay a roof claim. Tell us the age and the material up front so we shop the right ones the first time.
What is a wind and hail deductible?
A separate, usually larger deductible that applies only to storm damage, often written as a percentage of the dwelling amount rather than a dollar figure. Always worth reading before you compare two prices.
Can you insure a mobile home?
Yes. It is a different policy from a standard homeowners one and a shorter list of carriers writes it, which is exactly the situation an independent agency is for.
My bank needs proof of insurance.
We send it to them directly. Your lender can also request documents themselves — send them to our lienholder page and it goes straight into the right hands.
Let us take a second look.
Start online and an agent picks it up, or call and we will do the whole thing with you. In English or Spanish, whichever the conversation starts in.