 Apollo
More than just an online quote
Simple online. Personal where it matters. Start your quote online, have a licensed agent review your options, and count on us to keep an eye on your policy. If a better option comes up, we’ll be here to help you take a look.
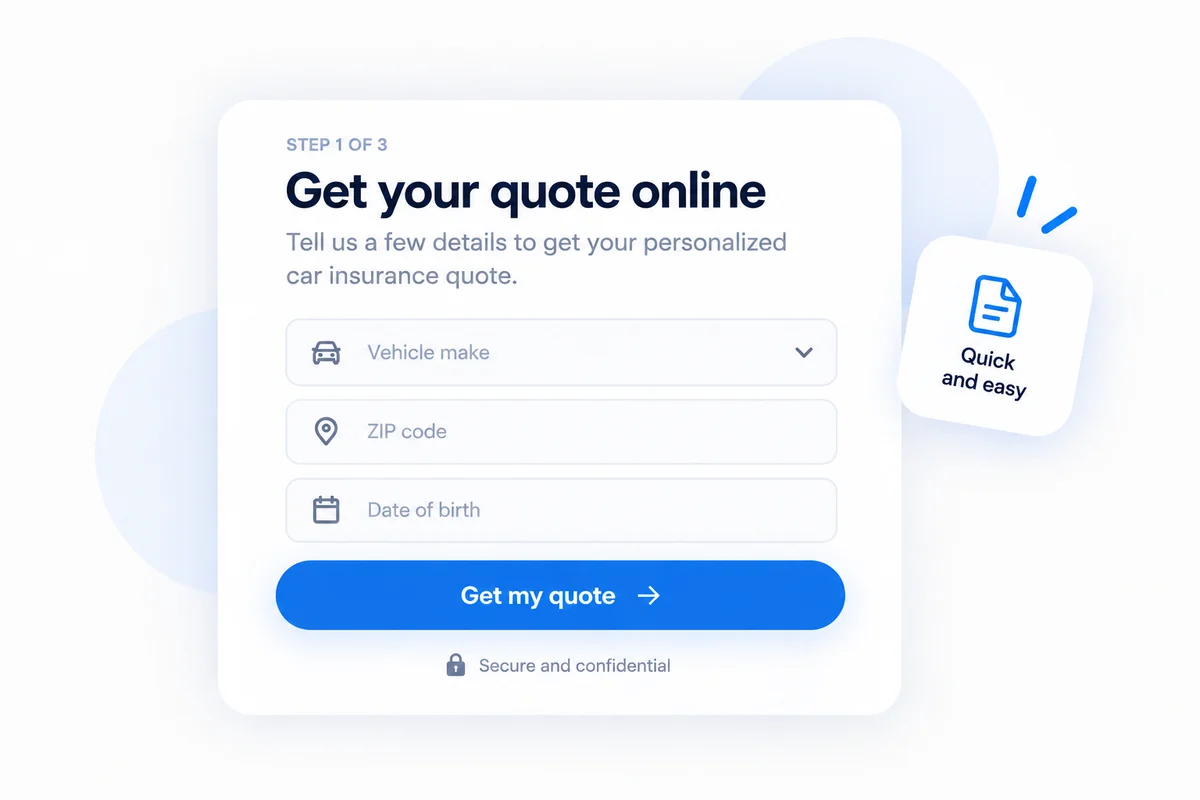
Get your quote online
Start with a simple online form. No long back-and-forth, no complicated process — just a faster, easier way to start shopping for coverage.
A real person reviews your options
Not just a quote — a quote checked by a person. Our technology helps gather and compare options, then a licensed Safe House agent reviews your rates, coverage, and details to help you find the right fit.
Illustration only — the figures shown are not real quotes.
We watch for better rates
We keep an eye on your policy, let you know when better options come up, and help you stay on top of renewals — with real support in English or Spanish.
What the online price misses
Commercial is where an online quote stops being merely imprecise and starts being the wrong policy entirely.
A truck used for work, on a personal auto policy, is a claim waiting to be denied. It is the most expensive mistake in this category and it is invisible until the day it matters.
A personal auto policy can exclude business use outright. The truck is insured right up until the claim is for work, and then it is not. That is a five-minute conversation that saves a company.
Limits, additional insured, waiver of subrogation, primary and non-contributory. The customer or the landlord who hired you wrote those words into an agreement, and a quote that ignores them buys a policy that fails the audit.
- The limits the contract requires
- Additional insured wording
- Waiver of subrogation
- Primary and non-contributory
Employees, subcontractors, a family member on weekends. Who is scheduled and who is merely permitted changes both the price and whether a claim is paid.
- Every driver listed by name
- Motor vehicle records pulled
- Anyone excluded, in writing
Half of commercial insurance is documents — certificates, filings, additional insureds, lienholder letters. That is not a rating problem. It is a phone-answering problem, and it is the reason to have an agent at all.
Tell us the deadline when you call. A certificate takes minutes when the policy is already right and a week when it is not.
Anyone can show you a number. A licensed Safe House agent reads the quote before you buy it, asks the questions above, and re-shops it when the answers change something. It costs you nothing — it is what the commission on the policy is for.
We lay the options out. You pick.
Commercial cover is assembled, not bought off a shelf. What you need is decided by what you do and by what you have signed — so an agent reads both before quoting any of it.
What is included
- Commercial auto liability
- Physical damage on each unit
- Hired and non-owned auto
- Filings, where the state requires them
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →What is included
- Everything in commercial auto
- General liability
- Certificates for the people who need them
- Additional insured endorsements
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →What is included
- Everything in auto plus general liability
- Cargo coverage
- Tools and equipment
- Waivers and contract wording
- Certificates issued the same day
Availability and wording vary by company and by state. Your agent confirms what each one costs and what it actually says before anything is bought.
Start my quote →$•••/mo$•••/moYour two numbers, side by side — from a real quote, in about five minutes.
Compare between companies
The same driver, the same car, the same coverage — and the companies disagree, often by hundreds. One quote cannot tell you whether you are being charged too much, because there is nothing to compare it against. We put your details to every company we represent and show you what each one said.
A human reads every policy. That is the whole product. The form is the fast part; the part worth paying an agency for is somebody who has placed this a thousand times looking at what came back before you buy it.
Who we write
Small operations, mostly. The ones a national carrier treats as a rounding error and a broker will not return a call about.
What people ask us
I use my truck for work sometimes. Is my personal policy enough?
Often not, and that is the single most expensive assumption in this category. Tell us how the vehicle is actually used and we will tell you straight whether it needs a commercial policy.
My customer needs a certificate today.
Call us. Certificates are usually the same day, and if your contract needs specific wording — additional insured, waiver of subrogation — send it and we will match it.
Can you do federal or state filings?
Yes, where the operation requires them. Tell us what you are hauling, where and under whose authority, because that decides which filings apply.
How do you insure a fleet?
Vehicle by vehicle, and then as one policy. Deductibles and coverage do not have to be identical across every unit, and on a mixed fleet they usually should not be.
What about my tools and equipment?
Not covered by the auto policy. That is a separate coverage and it is the gap we find most often on policies written elsewhere.
Do you cover businesses in New Mexico?
Yes — we are licensed in both states. Commercial quotes are prepared by an agent either way, because this is not a product that should be bought off a form.
Let us take a second look.
Start online and an agent picks it up, or call and we will do the whole thing with you. In English or Spanish, whichever the conversation starts in.